

This article is part of the thematic channel The Carbon Observer: subscribe to the newsletter
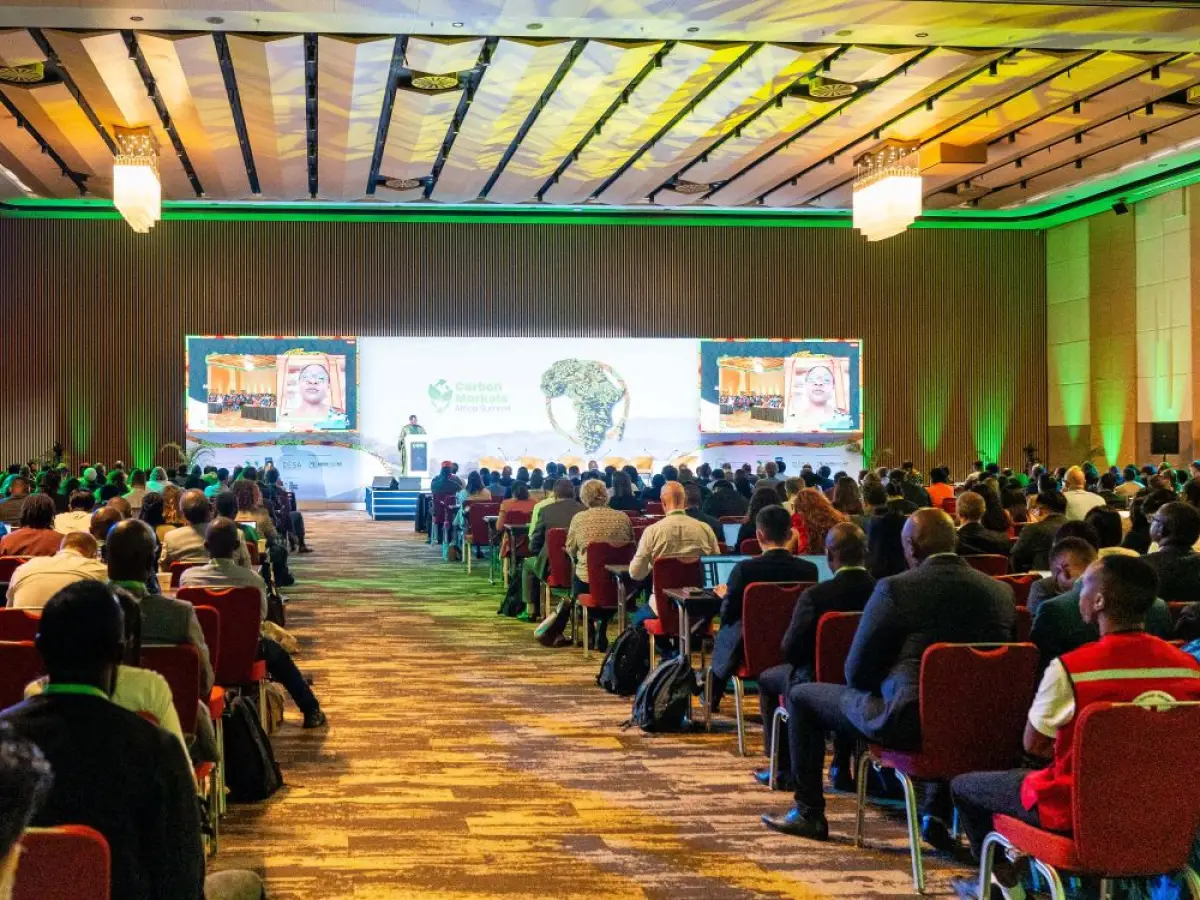
Kigali - I wrote this op-ed from the Carbon Markets Africa Summit in Kigali, a great event that brought together investors, project developers and governments committed to making Africa a major hub for Article 6 carbon markets. One message particularly resonated with me. In her keynote speech, Rwanda's Minister of Environment emphasised that Africa needs bankable projects capable of attracting investment and supporting economic development.
And that is exactly the point. Carbon finance could play a central role in mobilising capital, creating jobs and supporting a more sustainable development pathway. But something caught my attention: across discussions, meetings and keynote speeches, plenty about carbon finance and investment opportunities was discussed. Yet, Article 6.4 and its Paris Agreement Crediting Mechanism (PACM) were almost absent from the conversation.
For many of the people actually developing and financing projects, Article 6.4 remains more of a theoretical framework than a practical opportunity. Developers do not really oppose the mechanism, they simply do not see a compelling reason to adopt another complex system in a market that is already extremely difficult to navigate.
Developers are already dealing with changing methodologies, host-country authorisations, corresponding adjustments and increasingly demanding buyer requirements. Article 6.4 introduces yet another set of rules and approval processes without demonstrating a clear commercial advantage.
After years of negotiations, the mechanism is finally becoming operational. As of October 2026, five methodologies have been approved, including two new clean-cooking methodologies. Meanwhile, 1,512 projects and programmes have requested transition from the old Clean Development Mechanism (CDM), with 418 having received host-country approval by June. Transitioning existing projects, however, is not the same as attracting new investment under the new methodologies.
In conversations with experts and developers, one concern kept emerging: methodological conservatism increasingly seems to be treated as synonymous with environmental integrity. Stricter baselines and more demanding monitoring requirements could significantly reduce credit issuance. Developers must also account for mandatory deductions of 5% for the Adaptation Fund and at least 2% for overall mitigation, alongside administrative fees, host-country levies and, where applicable, reversal-risk buffer contributions.
To understand the potential economic impact, I ran a quick-and-dirty simulation. This is not a financial model or an Article 6.4 price forecast, just a simple exercise to illustrate how project economics could change.
Let's assume a project originally generates 100,000 credits annually, sold at $10 each, generating $1 million in carbon revenue. If more conservative accounting reduces issuance by 40%, and we apply the mandatory 7% UNFCCC deductions, only 55,800 credits remain available for sale. What price would the developer need to charge to maintain the same carbon revenue?

In the most demanding scenario, a credit previously sold at $10 would need to sell for almost $30 just to preserve the same carbon revenue. Is the market prepared to pay that difference? The concern is not conservatism itself, but the accumulation of conservative assumptions without sufficiently recognising improvements already made to address historical over-crediting. Conservatism should ensure accurate crediting, not become an objective in itself.
Meanwhile, international carbon markets are progressing. According to Sylvera, projected demand for internationally adjusted credits under CORSIA and government purchasing programmes could approach one billion tonnes through 2030.
Unlike Article 6.4, these pathways can leverage established standards, methodologies and registries that developers already know, and which are beginning to support deliveries to governments and airlines. Why move to an entirely new mechanism when existing systems are already opening access to compliance markets? The answer may come from future demand.
The European Commission has proposed auctioning up to 260 million EU ETS allowances to finance the purchase of international credits between 2036 and 2040. At an illustrative EUA price of €120 in the late 2030s, this could generate approximately €31 billion in purchasing resources. This is not a guaranteed budget or credit price, but it illustrates the scale of the potential opportunity.
Such purchasing power could make Article 6.4 more attractive, establish a new market benchmark and potentially encourage other countries to follow a similar approach. But this raises two fundamental questions. Will buyers pay the higher prices needed to make these projects viable, while keeping international credits cost-effective? And perhaps more importantly, will enough eligible and authorised credits be available?
Lower issuance per project means more investment is needed to generate the same volume. Host-country authorisation remains a sovereign decision, while credit-vintage eligibility and restrictions across NDC periods create additional uncertainty.
For Europe, securing up to 260 million credits between 2036 and 2040 would require a substantial project pipeline developed and financed years in advance. The market cannot wait until 2036 to start developing the projects Europe may need in 2036. This brings me back to the message from Rwanda's Minister of Environment: “Africa needs bankable projects.”
Article 6.4's success will ultimately depend on strong demand signals and its ability to reduce risks for project developers and investors. This means simplifying procedures, providing greater regulatory certainty, establishing a clear and transparent pathway for host-country authorisation, and turning regulatory ambition into bankable projects that attract capital and deliver measurable results.
Cover: the opening of the Carbon Markets Africa Summit (CMAS) 2026 in Kigali, photo by VUKA Group